Schedule a free consultation
We dislike spam as much as you do.
Your information is safe with us.
Explore the difference between Guidance Residential's Declining Balance Co-ownership Program and other home financing options.
Conventional Banks or Mortgage Companies |
![]() |
Subsidiaries of Banks or Mortgage Companies |
|
| Muslim Owned & Managed | No | Yes | No |
| Not A Bank | No | Yes | No |
| Riba-Free | No | Yes | No |
| Authentic Musharakah Model | No | Yes | No |
| Real Co-Ownership Created via LLC | No | Yes | No |
| Risk Sharing | No | Yes | No |
| Diverse, World-Renowned Shariah Board | No | Yes | No |
| Non-Recourse Commitment | Variable | Yes | Variable |
| Promotes Community-Conscious Financing | No | Yes | No |
| Promotes Circulation of Wealth Within Community | No | Yes | No |
| Switch to guidance | Pre Qualify Now | Switch to guidance |
What each point in the comparison above means.
Yes. Guidance Residential is Muslim owned and managed, so the company's values and mission are aligned with the needs of the Muslim community.
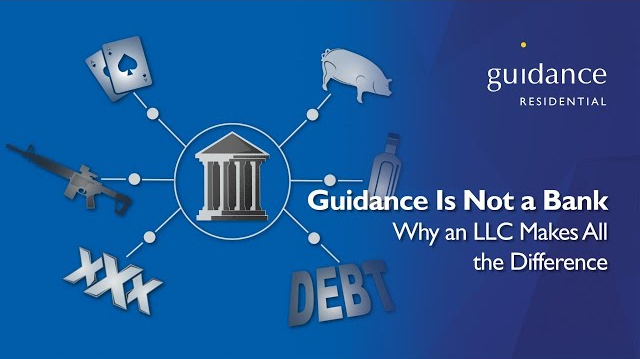
No. Guidance Residential is a non-bank, Shariah-compliant home financing provider that is not affiliated with a bank or riba-based lender. Many providers that label products as "Islamic" are affiliated with banks that earn money through riba.
Yes. The Declining Balance Co-ownership Program does not involve the payment of interest, and the entire institution is 100% riba-free.
Guidance Residential's Declining Balance Co-ownership Program is a Musharakah, or equity partnership, in which homeowners receive the benefits of ownership while making acquisition payments. It conforms to the Islamic principle of sharing risk and reward, unlike Ijarah (rent-to-own) or Murabaha (mark-up resale) models, and it does not create debt.
An LLC is formed to establish Guidance Residential's co-ownership in the property. This lets Guidance Residential avoid trading in debt and offer a truly Shariah-compliant contract with real risk-sharing.
If the property is lost through a natural disaster or eminent domain and there is a shortfall in the insurance or government proceeds, the loss is shared based on each party's percentage of ownership. Conventional providers first pay off the loan before sharing any remaining proceeds with the homeowner.
Yes. Guidance Residential has a large, diverse, independent Shariah Board of globally recognized scholars, headed by Justice Muhammad Taqi Usmani, who also chairs the Shariah Board for the Accounting and Auditing Organization for Islamic Financial Institutions (AAOIFI). Read more about our independent Shariah Board.
If the customer defaults, Guidance Residential does not pursue the customer's other assets such as personal savings, pensions, or college funds. The customer is only at risk for their equity position in the property.
Guidance Residential was founded on a clear set of values and a mission to provide a responsible alternative to conventional home financing through a risk-sharing, co-ownership model. Unlike many providers, Guidance operates independently of banks and lenders, who provide financing to any qualified applicant, regardless of the social impact that applicant may have on society (ie., alcohol or gambling).
As one of the few Muslim-owned Islamic finance institutions in the U.S., Guidance Residential helps American Muslims achieve long-term financial security and generational wealth through Islamic home financing. Guidance supports Muslim American nonprofits as a corporate sponsor. By keeping wealth circulating within the Muslim community and supporting initiatives that benefit the ummah, Guidance fosters a sustainable economic ecosystem that creates lasting value for current and future generations.
How does Islamic financing work?